
Change the state. Keep the company.
Move your corporation out of Delaware via redomestication.
Start the process of transferring your corporation out of Delaware in under five minutes.
Keep your existing contracts, credit history, and EIN.
Handled by a dually licensed attorney and CPA.
100% online. Flat-fee. No sales call required.





Executive Summary
Redomestication is the legal process of transferring a company out of Delaware to Florida, maintaining the existing federal employer identification number (FEIN), contracts, bank accounts, and in most cases, corporation name.
- No Downtime: When executed by a professional, there is no operational or financial disruption.
- Complexity: This process exists at the intersection of federal tax law and the laws of Florida and Delaware. It is not a "DIY" weekend project.
- Timeline: Redomestication takes about three months from start to finish, and expedite options are available. The intake process is entirely electronic, takes less than five minutes to get started, and can be completed on our redomestication platform here.
- Credentials: All work is handled by a dually-licensed attorney and CPA.
- Pricing: Pricing varies depending on the size of the company and is flat-fee.
- Get Started: No need to "request a quote." The exact price can be seen in under 30 seconds at the above link.
Move your corporation from Delaware to Florida without turning it into a second job.
You can see the exact price in under 30 seconds, complete the online intake in less than five minutes, and receive the documents for e-signature within 48 hours.
Seven answers you should demand before hiring anyone to redomesticate your corporation.
A redomestication from Delaware to Florida should not begin with uncertainty about price, timing, responsibility, or what happens if the filing encounters a problem.
| Ask this before you hire anyone | Cummings & Cummings Law | Any other provider |
|---|---|---|
| Can I see my exact price before I engage you? |
Yes. See the exact price online in about 30 seconds.
|
Often requires a sales call. Ask for the complete price in writing before you provide payment information. |
| How much of my time will the intake require? |
Less than five minutes for the online intake in a typical matter.
|
Ask whether calls, meetings, questionnaires, or manual document exchanges are required. |
| When will my legal documents be prepared? |
Within 48 hours after engagement and receipt of the required information. Faster if you choose to expedite.
|
Sometimes weeks. Ask for a specific preparation deadline, not an open-ended estimate. |
| Who actually prepares the legal work? |
Prof. Chad D. Cummings, CPA, Esq., M.S.T., LL.M., CMA, CFE, CIA, CRMA, CISA, CITP, FCPA, PFS, CFP personally prepares every document.
|
Confirm the name and credentials of the professional. Will it be an attorney, CPA, intern, paralegal? Where are they based? |
| Who submits and manages the state filings? |
We submit the required filings in Delaware and Florida and address
filing-office inquiries during the process.
|
Confirm whether the provider files both sides of the transaction or leaves part of the process to you. |
| Will I receive status updates while the states review the filings? |
Yes. We provide weekly status updates via email every Friday at no additional charge.
|
Many firms only provide updates upon request. Ask how often you will receive an update and whether updates cost extra. |
| What happens if the redomestication cannot be completed? |
We will refund your filing costs and 120% of the legal fees you paid if we are unable to obtain the approval of the Department of State.
|
Ask for the provider's remedy in writing before you engage the provider. Check their credentials and track record with the state bar, BBB, and Google Reviews. |
Redomestication changes where your corporation is domiciled, not the identity of the business itself.
When handled by a professional, the same legal entity continues uninterrupted from Delaware to Florida with no operational or financial disruption.
- Existing legal entity
- Existing FEIN
- Existing contracts
- Existing bank accounts
- Existing credit history
- Existing business history
- Same legal entity
- Same FEIN
- Same contracts
- Same bank accounts
- Same credit history
- Same business history
You provide the information and signatures. We take it from there.
Our engagement is designed for one task: changing the domicile of your corporation from Delaware to Florida while preserving the company's continuity.
If our redomestication process does not fit your corporation, we will tell you.
If the information you provide shows that our redomestication service cannot be used to move your corporation from Delaware to Florida, we will refund all of your costs and fees and inform you promptly before any instruments are filed. We will not waste your time or money.
In this circumstance, we will also suggest alternatives to explore with your tax professional, including referrals, where appropriate.
Your Redomestication Closing and Tax Continuity Packet.
After the redomestication from Delaware to Florida is complete, we deliver the closing materials and practical next-step instructions for you and your tax professional.
How to transfer your company to Florida and keep the EIN with zero downtime [step-by-step]
How to move a corporation from Illinois to Florida [step-by-step process]
How to transfer an Illinois LLC to Florida and keep the EIN [step-by-step]
Attorney and CPA: How to transfer a corporation to Florida from Georgia [step-by-step]
Attorney and CPA: How to move an LLC from Georgia to Florida [step-by-step]
How to transfer a corporation out of New York to Florida [step-by-step]
How to transfer an LLC out of New York to Florida [step-by-step]
Steps to transfer a company (LLC or corporation) to Florida
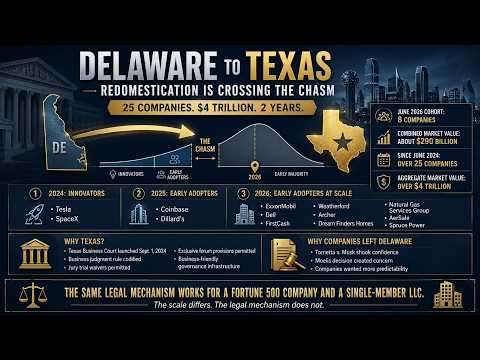
Report: #DEXIT is just getting started, and the Delaware exodus to Texas continues.

How to Transfer a Company to Texas in 2026: Dell Announces its Redomestication From Delaware [DEXIT]
50 State Series: How to move your LLC or corporation out of Delaware and keep your EIN
Report: Billionaire Stephen Ross says South Florida’s business relocation push in the '1st inning'
How to transfer your company to Florida and keep the EIN with zero downtime [step-by-step]
How to move a corporation from Illinois to Florida [step-by-step process]
How to transfer an Illinois LLC to Florida and keep the EIN [step-by-step]
Attorney and CPA: How to transfer a corporation to Florida from Georgia [step-by-step]
Attorney and CPA: How to move an LLC from Georgia to Florida [step-by-step]
How to transfer a corporation out of New York to Florida [step-by-step]
How to transfer an LLC out of New York to Florida [step-by-step]
Steps to transfer a company (LLC or corporation) to Florida
Report: #DEXIT is just getting started, and the Delaware exodus to Texas continues.
How to Transfer a Company to Texas in 2026: Dell Announces its Redomestication From Delaware [DEXIT]
50 State Series: How to move your LLC or corporation out of Delaware and keep your EIN
Report: Billionaire Stephen Ross says South Florida’s business relocation push in the '1st inning'
Redomestication, also known as redomesticating, refers to the lesser-known legal process of transferring or moving the "home state" of an existing corporation, partnership, or LLC to a new state. It means keeping your existing company name, credit, and federal employer identification number (FEIN) without wasting time and money creating a new business entity, applying for foreign registration, or moving assets between companies.
— Prof. Chad D. Cummings, CPA, Esq., M.S.T., LL.M., CMA, CFE, CIA, CRMA, CISA, CITP, FCPA, PFS, CFP
Florida destination-state requirements
A same-form corporate domestication into Florida is governed by Fla. Stat. §§ 607.11920-607.11924; a conversion involving a different entity form is governed by §§ 607.11930-607.11935. The transaction requires the applicable written plan, owner approval, and Florida filing instruments, coordinated with the Delaware outbound filing so the same corporation continues without interruption. Professional corporations may also require compliance with Chapter 621.
Tax considerations when moving a corporation from Delaware to Florida
Delaware's individual income tax reaches 6.6%, while its corporate income tax is 8.7% on taxable income allocated or apportioned to Delaware. Incorporation in Delaware alone does not necessarily create corporate income tax when the corporation conducts no business there; annual franchise tax is a separate obligation. The Division of Revenue corporate tax guidance explains this distinction. An LLC taxed as a corporation follows the corporate rules, while partnership or disregarded classification generally shifts ordinary income tax to the owners.
Delaware has no general state or local sales tax, but it imposes gross receipts tax on many sellers and service providers. Published ordinary rates range from 0.0945% to 1.9914%, with activity-specific exclusions and special rules. Gross receipts tax can apply even when a business has little net profit because ordinary operating expenses are not deducted in the same way as under an income tax. A Delaware business license can also remain necessary after an outbound conversion if Delaware activity continues.
Annual entity charges deserve separate attention. A Delaware LLC generally owes a $300 annual tax. Corporations calculate franchise tax under the authorized-shares or assumed-par-value-capital method; the minimum is $175 under the first method and $400 under the second, plus the applicable annual-report fee. The Division of Corporations tax instructions explain the calculation and higher caps for certain large corporations. A $400 minimum should not be presented as applying to every Delaware corporation, and these charges should not be confused with the 8.7% income tax.
Delaware currently imposes neither an estate tax nor an inheritance tax. Real estate remains subject to county and local property taxes. The owner's personal residency and the business's income sources still matter when comparing Delaware with Florida; moving the charter does not itself relocate either one.
Before redomesticating your corporation from Delaware to Florida, reconcile current-year franchise tax and any prior balances with the Division of Corporations. Then determine whether income-tax, gross-receipts-tax, and licensing accounts should close or remain active with the Division of Revenue. Continuing Delaware operations can require foreign qualification and future filings even after the original Delaware domestic status ends. Retain the accepted conversion and the tax calculations supporting the final or continuing returns.
For a small corporation, choosing the permitted franchise-tax calculation method can materially change the annual charge. Compare both methods using the actual authorized shares and capital figures before finalizing the conversion budget.
Florida imposes no individual income tax. A qualifying Florida resident therefore does not pay Florida income tax on wages, investment income, or ordinary pass-through business income. The state generally taxes C corporation income at 5.50 percent after Florida adjustments, apportionment, and the $50,000 exemption. An LLC classified as a corporation follows the corporate rules; an LLC's legal label alone does not determine its tax treatment. S corporations can have Florida corporate-tax obligations on certain federally taxable built-in gains or excess net passive income. A partnership or LLC taxed as a partnership can also have a Florida Form F-1065 filing obligation when it has a corporate owner; pass-through treatment does not make every information return unnecessary. The Florida Income Tax Code explains classification and filing requirements.
Florida's general sales tax is 6.00 percent, with county surtaxes where applicable. Effective October 1, 2025, Florida repealed sales tax and the related discretionary surtax on commercial real-property rentals. The enacted 2025 repeal provision in section 37 of H.B. 7031 establishes the effective date. Transient accommodations, parking, and other separately taxable rental transactions require their own analysis. Florida has no current separate estate or inheritance tax, but moving a business does not itself establish an owner's Florida domicile or entitlement to homestead benefits.
Redomesticating a corporation from Delaware to Florida can reduce the costs of maintaining a company under a state law that no longer matches its operations. Tax savings depend on the owners' residence, tax classification, and where the business actually earns income. Employees, property, inventory, or other business activity remaining in Delaware can preserve its income-tax, sales-tax, payroll, or registration obligations. Complete any required final returns before closing accounts.
Economic nexus also matters for an out-of-state seller without a physical office. South Dakota v. Wayfair, Inc., 585 U.S. 162 (2018), rejected the physical-presence prerequisite for sales-tax collection. A different, limited protection applies to certain solicitation of orders for tangible personal property under 15 U.S.C. § 381. Wisconsin Department of Revenue v. William Wrigley, Jr., Co., 505 U.S. 214 (1992), addresses that net-income-tax protection. It is not a general exemption from sales taxes or taxes on services. A state-by-state nexus review should identify each tax, applicable threshold, protected activity, and continuing filing duty.
Specific legal requirements to transfer a corporation to Florida from Delaware
Delaware has state-specific statutory, approval, filing, fee, and sequencing requirements that must be coordinated with Florida law. The requirements below are the origin-state requirements applicable to this transaction.
- Delaware uses outbound conversion to continue an LLC or corporation in another state. 6 Del. C. § 18-216 permits a Delaware LLC to become a foreign LLC or another listed entity. 8 Del. C. § 266 permits a Delaware corporation to become a foreign corporation or another authorized business form. The applicable certificate is a Certificate of Conversion to Non-Delaware Entity. Confirm the law of Florida permits the corresponding continuation and identify whether your corporation will retain its current type. Delaware's separate non-U.S. domestication and transfer provisions should not be used interchangeably with an ordinary interstate conversion.
- An LLC's agreement controls the initial approval analysis. Under § 18-216(b), apply the LLC agreement's conversion provision first. If it has no conversion provision and does not prohibit conversion, apply its merger or consolidation approval provision. If neither exists, the current default generally requires members holding more than 50% of the current interests in profits. That is an economic-interest measure, not necessarily a headcount or a majority of managers. An LLC agreement can also prohibit conversion. Read the actual agreement and amendments before deciding the required vote, and preserve the signed approval and the ownership schedule used to calculate it.
- Check the grandfather rule for older Delaware LLCs. The current § 18-216(b) preserves the pre-August 2015 default for an LLC whose original certificate was filed and effective on or before July 31, 2015, unless its agreement provides otherwise. That older default required approval by all members when the agreement lacked the relevant conversion or merger rule. Consequently, the newer more-than-50% rule should not be applied automatically to a longstanding LLC with a silent agreement. Confirm the original effective date and the agreement's terms. If the record is ambiguous, resolve the approval question before submitting a certificate that declares the conversion properly authorized.
- A corporation requires the corporate approval process. 8 Del. C. § 266(b) calls for a board resolution approving the conversion and recommending stockholder approval, followed by approval from a majority of outstanding shares entitled to vote, subject to any greater applicable requirement. For a meeting, notice is given to voting and nonvoting holders at least 20 days beforehand. A stockholder who will become a general partner must separately approve that result. Review appraisal rights under § 262 and any charter or contractual protection before soliciting votes. Older descriptions requiring unanimous stockholder approval for every corporate conversion do not reflect the current statutory standard.
- Review older corporate merger restrictions. § 266(k) extends qualifying merger or consolidation restrictions in pre-August 2022 charters and specified stockholder agreements to a conversion unless the document expressly provides otherwise. A charter provision requiring a special vote for a merger may therefore matter even if it never mentions conversion. Compare the destination charter with the existing charter for any change in class rights or governance. The current statute also expressly permits an optional plan under § 266(l); when that plan is used, obtain the approval required for its provisions and include the corresponding certificate recital required by § 266(c)(7).
- Use a written transaction plan even where the Delaware statute does not require a separate filed plan. For an LLC, the agreement and destination law determine the required internal documentation; § 18-216 should not be described as universally demanding publication of a detailed plan. Record the resulting name and jurisdiction, the destination governing documents, and how existing interests continue or are exchanged. For a corporation using a statutory plan, reconcile it with the board resolution and stockholder action. Identify any cash or other consideration, the closing conditions, and who may implement a permitted correction. Keep private economic terms out of the public certificate unless they are required there.
- Complete the entity-specific certificate. The Division of Corporations publishes an LLC-to-non-Delaware template and a corporation-to-non-Delaware template. They ask for the current name, original name if changed, and date of the original Delaware formation filing. They also identify the destination jurisdiction and resulting entity name and include the appropriate approval recital. A corporation's template should be reviewed against the current statute if an optional plan adds a required statement. An authorized signer must execute the document in the appropriate capacity. Verify each factual field against the Delaware record and the final destination filing before submission.
- Preserve the required Delaware process appointment. Under § 18-216(e) for LLCs and § 266(c) for corporations, the outbound certificate includes consent to service in Delaware for the specified existing obligations and appoints the Secretary of State to receive process. The corporate provision also addresses obligations arising from conversion, including applicable appraisal proceedings. Provide a mailing address that will remain monitored after the move and update it when necessary. The end of Delaware domestic status does not erase liabilities or change the law applicable to earlier matters. Include responsibility for handling Delaware notices in the post-closing instructions.
- Use the published state fees and clear the tax balance. The current templates list $220 for an LLC conversion and $234 for a corporate conversion, with $9 for each additional corporate certificate page. A certified copy is an additional $50 under those instructions, and expedited service has separate charges. Before filing, the LLC instructions require payment of Delaware taxes through the effective date. The corporate instructions also require the applicable annual franchise-tax reports. Ask the Franchise Tax Section for the amount due through the proposed effective date. A balance calculated for an earlier closing can be insufficient when the effective date changes.
- Coordinate effectiveness with the destination rather than filing a separate dissolution. Delaware allows a future effective date or time within the governing filing rules. State the intended time consistently and confirm that the destination document legally continues the same entity. The conversion certificate ends the original Delaware domestic status as provided by the statute. A separate dissolution or LLC cancellation is not ordinarily needed to accomplish that same conversion and can introduce an inconsistent public record. Preserve both accepted filings and the evidence of when they became effective. If a closing condition fails before a delayed effective time, review the available amendment or termination filing immediately.
- The converted business retains assets and debts. § 18-216(c), (g), and (h) and § 266(e), (f), and (h) preserve continuity of the entity and its property and protect creditor rights. Conversion generally does not require liquidation or payment and distribution of all assets. Existing personal liability is not discharged by moving the entity. These provisions support continuity when communicating with banks or counterparties, but they do not guarantee the federal tax result. Review tax classification and EIN treatment in light of the specific transaction, especially where the plan changes entity type or the owners receive consideration beyond equivalent destination interests.
- Review agreements and assets that remain in Delaware or other states. A loan covenant may specifically restrict a change of jurisdiction, and a license can require a filing even where state entity law preserves continuity. Obtain any necessary consent before effectiveness and identify the documents that must be updated afterward. Real-estate title records and secured-party filings should be addressed with the title company or lender. If a Delaware LLC has protected or registered series, examine the series structure and destination recognition separately before applying a conventional single-entity conversion packet. The legal treatment of a series should not be inferred solely from the parent LLC's authority to convert.
- Account for Delaware's different annual tax calendars. The Division of Corporations payment guidance distinguishes corporations' March 1 annual-report and franchise-tax deadline from the June 1 annual-tax deadline for LLCs and the other covered alternative entities. A domestication budget should therefore identify the entity type, reporting year, and proposed effective date rather than treating every Delaware business as having the same deadline. Resolve the amount due through closing with the Franchise Tax Section and retain the calculation used. If the planned effective date changes, recheck the tax clearance before filing. Obtain a certified conversion copy when a bank or destination authority requires it and preserve it with the tax receipt; the two documents prove different parts of the closing.
- Complete the continuing-registration and tax decisions. If your corporation retains Delaware business after moving from Delaware to Florida, review foreign qualification and ongoing registered-agent requirements. Franchise taxes paid to the Division of Corporations are distinct from income tax, gross receipts tax, and business licensing administered by the Division of Revenue. Close or maintain each account according to continuing activity. Keep the approved plan or resolutions, owner approvals, tax clearance calculations, accepted certificates, and consent schedule together. Calendar the destination's first report and any Delaware foreign-entity obligations that will continue after the conversion.
