
Change the state. Keep the company.
Move your corporation out of Missouri via redomestication.
Start the process of transferring your corporation out of Missouri in under five minutes.
Keep your existing contracts, credit history, and EIN.
Handled by a dually licensed attorney and CPA.
100% online. Flat-fee. No sales call required.





Executive Summary
Redomestication is the legal process of transferring a company out of Missouri to Texas, maintaining the existing federal employer identification number (FEIN), contracts, bank accounts, and in most cases, corporation name.
- No Downtime: When executed by a professional, there is no operational or financial disruption.
- Complexity: This process exists at the intersection of federal tax law and the laws of Texas and Missouri. It is not a "DIY" weekend project.
- Timeline: Redomestication takes about three months from start to finish, and expedite options are available. The intake process is entirely electronic, takes less than five minutes to get started, and can be completed on our redomestication platform here.
- Credentials: All work is handled by a dually-licensed attorney and CPA.
- Pricing: Pricing varies depending on the size of the company and is flat-fee.
- Get Started: No need to "request a quote." The exact price can be seen in under 30 seconds at the above link.
Move your corporation from Missouri to Texas without turning it into a second job.
You can see the exact price in under 30 seconds, complete the online intake in less than five minutes, and receive the documents for e-signature within 48 hours.
Seven answers you should demand before hiring anyone to redomesticate your corporation.
A redomestication from Missouri to Texas should not begin with uncertainty about price, timing, responsibility, or what happens if the filing encounters a problem.
| Ask this before you hire anyone | Cummings & Cummings Law | Any other provider |
|---|---|---|
| Can I see my exact price before I engage you? |
Yes. See the exact price online in about 30 seconds.
|
Often requires a sales call. Ask for the complete price in writing before you provide payment information. |
| How much of my time will the intake require? |
Less than five minutes for the online intake in a typical matter.
|
Ask whether calls, meetings, questionnaires, or manual document exchanges are required. |
| When will my legal documents be prepared? |
Within 48 hours after engagement and receipt of the required information. Faster if you choose to expedite.
|
Sometimes weeks. Ask for a specific preparation deadline, not an open-ended estimate. |
| Who actually prepares the legal work? |
Prof. Chad D. Cummings, CPA, Esq., M.S.T., LL.M., CMA, CFE, CIA, CRMA, CISA, CITP, FCPA, PFS, CFP personally prepares every document.
|
Confirm the name and credentials of the professional. Will it be an attorney, CPA, intern, paralegal? Where are they based? |
| Who submits and manages the state filings? |
We submit the required filings in Missouri and Texas and address
filing-office inquiries during the process.
|
Confirm whether the provider files both sides of the transaction or leaves part of the process to you. |
| Will I receive status updates while the states review the filings? |
Yes. We provide weekly status updates via email every Friday at no additional charge.
|
Many firms only provide updates upon request. Ask how often you will receive an update and whether updates cost extra. |
| What happens if the redomestication cannot be completed? |
We will refund your filing costs and 120% of the legal fees you paid if we are unable to obtain the approval of the Secretary of State.
|
Ask for the provider's remedy in writing before you engage the provider. Check their credentials and track record with the state bar, BBB, and Google Reviews. |
Redomestication changes where your corporation is domiciled, not the identity of the business itself.
When handled by a professional, the same legal entity continues uninterrupted from Missouri to Texas with no operational or financial disruption.
- Existing legal entity
- Existing FEIN
- Existing contracts
- Existing bank accounts
- Existing credit history
- Existing business history
- Same legal entity
- Same FEIN
- Same contracts
- Same bank accounts
- Same credit history
- Same business history
You provide the information and signatures. We take it from there.
Our engagement is designed for one task: changing the domicile of your corporation from Missouri to Texas while preserving the company's continuity.
If our redomestication process does not fit your corporation, we will tell you.
If the information you provide shows that our redomestication service cannot be used to move your corporation from Missouri to Texas, we will refund all of your costs and fees and inform you promptly before any instruments are filed. We will not waste your time or money.
In this circumstance, we will also suggest alternatives to explore with your tax professional, including referrals, where appropriate.
Your Redomestication Closing and Tax Continuity Packet.
After the redomestication from Missouri to Texas is complete, we deliver the closing materials and practical next-step instructions for you and your tax professional.
How to transfer a company to Texas: keep the EIN with no downtime [step-by-step]
How to transfer a corporation to Texas from New York [step-by-step]
How to transfer an LLC from New York to Texas [step-by-step]
How to transfer a corporation to Texas [step-by-step]
How small business owners are transferring their LLCs to Texas [step-by-step]
How to legally move a company to Texas without starting over [step-by-step]
Transferring your business to Texas with no downtime [step-by-step]
How to transfer a corporation to Texas and keep the EIN [step-by-step]
How to transfer your LLC to Texas with no downtime [step-by-step]
How to move a company to Texas without disruption [step-by-step]

How to convert your company to Texas [step-by-step]

How to move your LLC or corporation to Texas from New York [step-by-step]
How to transfer a company to Texas: keep the EIN with no downtime [step-by-step]
How to transfer a corporation to Texas from New York [step-by-step]
How to transfer an LLC from New York to Texas [step-by-step]
How to transfer a corporation to Texas [step-by-step]
How small business owners are transferring their LLCs to Texas [step-by-step]
How to legally move a company to Texas without starting over [step-by-step]
Transferring your business to Texas with no downtime [step-by-step]
How to transfer a corporation to Texas and keep the EIN [step-by-step]
How to transfer your LLC to Texas with no downtime [step-by-step]
How to move a company to Texas without disruption [step-by-step]
How to convert your company to Texas [step-by-step]
How to move your LLC or corporation to Texas from New York [step-by-step]
Redomestication, also known as redomesticating, refers to the lesser-known legal process of transferring or moving the "home state" of an existing corporation, partnership, or LLC to a new state. It means keeping your existing company name, credit, and federal employer identification number (FEIN) without wasting time and money creating a new business entity, applying for foreign registration, or moving assets between companies.
— Prof. Chad D. Cummings, CPA, Esq., M.S.T., LL.M., CMA, CFE, CIA, CRMA, CISA, CITP, FCPA, PFS, CFP
Texas destination-state requirements
A redomestication into Texas is governed by Chapter 10, Subchapters C and D, of the Texas Business Organizations Code together with the law of Missouri. The transaction requires a written Plan of Conversion, the approvals required by the governing documents and applicable law, a Certificate of Conversion, and, for a Texas filing entity, a Certificate of Formation. The Texas filing must be coordinated with the Missouri outbound instrument so the same corporation continues without interruption.
Tax considerations when moving a corporation from Missouri to Texas
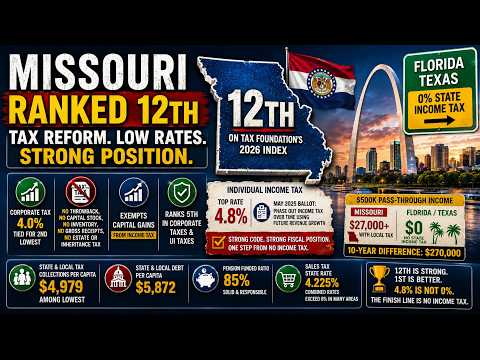
Missouri's top individual income tax rate is 4.70 percent for 2026, while the corporate income tax rate is 4.00 percent. Under Mo. Rev. Stat. § 143.121, individuals may subtract 100 percent of federally reported capital-gain income for tax years beginning January 1, 2025. This benefit can matter when an owner sells a business, but it is not a blanket exemption for every taxpayer or every sale receipt. Ordinary-income recapture is not converted into a capital gain. The general corporate capital-gain subtraction becomes available only for tax years after the individual top rate falls to 4.50 percent or lower. An electing pass-through entity cannot itself claim the individual subtraction, as the Department of Revenue's guidance explains. Eligible partnerships and S corporations can separately elect the SALT Parity Act tax, with owner credits.
Missouri's general state sales tax is 4.225 percent, plus applicable local taxes. Qualifying food receives a reduced 1.225 percent state rate, while local food taxes generally remain. The state does not impose a current estate or inheritance tax; its estate-tax guidance explains the cessation for deaths from 2005 onward. For a corporation redomesticating from Missouri to Texas, distinguish an owner's stock sale from the entity's asset sale and model the relevant tax classification before closing. The capital-gain subtraction does not make the transaction federally tax-free. Continuing Missouri-source operations or taxable sales can preserve Missouri obligations even after the entity's governing jurisdiction changes.
The 2026 withholding tables reflect the current 4.70 percent top individual rate. The capital-gain subtraction is already effective for eligible individuals; the separate corporate trigger should be monitored for later years. Owners should preserve the federal gain calculation and Missouri subtraction records for the year of the actual sale.
Texas imposes no individual income tax and prohibits a tax on individuals' net income under Texas Constitution article VIII, section 24-a. Texas also has no conventional corporate net income tax. Its franchise tax, however, applies to many corporations, LLCs, and other taxable entities, including businesses treated as pass-through entities for federal income-tax purposes. A federal S corporation election or partnership classification does not, by itself, exempt the business from Texas franchise-tax law.
For 2026 and 2027 report years, the franchise-tax no-tax-due threshold is $2.65 million in annualized total revenue. The general rates are 0.375 percent for qualifying retail or wholesale businesses and 0.75 percent for other businesses, applied to the taxable margin apportioned to Texas. Eligible businesses with no more than $20 million in annualized revenue can use the EZ computation at 0.331 percent, subject to its separate rules. The Texas Comptroller's franchise-tax guidance provides the current thresholds and methods. The threshold is not a deduction from taxable margin and does not establish that all income above it is taxed at the general rate. The compensation deduction limit is $480,000 per person for these report years. Compare the available margin methods using the business's actual revenue, eligible costs, compensation, and Texas apportionment before choosing a computation method.
Businesses at or below the revenue threshold generally no longer file a No Tax Due Report for report years 2024 and later, but an applicable Public Information Report or Ownership Information Report remains required. The ordinary annual deadline is May 15. Texas's state sales tax is 6.25 percent, with local taxes bringing the combined rate as high as 8.25 percent. Sales-tax, unemployment, property-tax, and licensing obligations may continue even when no franchise tax is payable. Texas has no current separate estate or inheritance tax.
Redomesticating a corporation from Missouri to Texas changes its governing jurisdiction. Actual tax savings depend on the owners' residence, the company's classification, and the location of its operations and receipts. Continuing employees, property, inventory, or qualifying sales in Missouri can preserve that state's filing and payment obligations. Do not close an account merely because the Texas conversion documents have been accepted.
South Dakota v. Wayfair, Inc., 585 U.S. 162 (2018), permits sales-tax nexus without the former physical-presence prerequisite. 15 U.S.C. § 381 instead provides limited net-income-tax protection for specified solicitation of tangible-goods orders. Wisconsin Department of Revenue v. William Wrigley, Jr., Co., 505 U.S. 214 (1992), interprets that protection. These authorities address different taxes and activities. Review nexus separately for each state, including remote sales and post-move operations, before projecting that redomestication will eliminate a former state's tax burden.
Specific legal requirements to transfer a corporation to Texas from Missouri
Missouri has state-specific statutory, approval, filing, fee, and sequencing requirements that must be coordinated with Texas law. The requirements below are the origin-state requirements applicable to this transaction.
- Missouri corporations have a direct outbound conversion procedure; an LLC generally uses an interstate merger for a same-type move. Mo. Rev. Stat. 351.409 permits a domestic business corporation to convert to another business entity, including a foreign corporation, subject to the statute and destination law. An LLC can use the interstate merger provisions in 347.127 through 347.133 with a destination survivor. These are materially different routes for a corporation moving from Missouri to Texas. The corporation should not be told that Missouri universally prohibits direct conversion, and the LLC merger should not be described as the same legal event as a corporation's direct continuation under another jurisdiction.
- Direct corporate conversion requires an unusually high shareholder approval threshold. Section 351.409 requires a board resolution approving the conversion and recommending it to stockholders. The meeting notice must be given at least 20 days beforehand to stockholders, including nonvoting holders. The conversion then requires approval by all outstanding shares, voting and nonvoting. A majority or ordinary merger vote is insufficient for this direct statutory route. Confirm the full capitalization and ownership record before choosing it, particularly where preferred or otherwise nonvoting stock remains outstanding. If unanimous approval is unavailable, another permissible structure must be assessed under its own statute and approval requirements.
- The corporate Certificate of Conversion must identify the company's history and destination. Section 351.409 requires the current corporate name and original name if different, the original incorporation date, the destination entity type and name, and the jurisdiction governing the resulting organization. Include the required approval recital and Missouri service-of-process consent, with the address for forwarding covered process. Prepare the destination organizational documents and reconcile the treatment of each share with the approved transaction. The certificate's future effective time must comply with the applicable Missouri filing rules and destination law. The closing record should show acceptance in both jurisdictions before the company is represented as having completed its conversion.
- The corporation continues as the same entity under the conversion statute. Section 351.409 preserves the business's identity and existing property and liabilities, while its Missouri corporate existence is replaced by its status under the destination's law. The statute does not ordinarily require a separate winding up or distribution of assets. Its rules also address pre-conversion obligations and the governing law for historical matters. A creditor's claim or personal guaranty is not erased by conversion. Record the original incorporation date and keep the accepted conversion evidence available for banks or counterparties. Federal tax classification and EIN treatment remain separate questions, especially if the transaction also changes ownership or organizational form.
- An LLC relocation through merger requires a destination survivor and a written agreement. Section 347.127 permits the relevant domestic and foreign LLC merger. Section 347.128 requires the Agreement of Merger, including the participating entities and survivor, the transaction terms, and the manner in which membership interests are converted. Organize the destination survivor and approve its governing documents before effectiveness. Explain how any initial destination interest is treated so that the final capitalization matches the approved exchange. The Missouri LLC should be identified as a nonsurviving constituent where the intended result is a business organized solely under Texas law.
- The LLC's default approval rule is unanimity, subject to the operating agreement. Section 347.079 generally requires all members to approve the merger unless the operating agreement provides otherwise. Review any separate class rights and obtain the destination LLC's approval under its governing law. The agreement should identify who may authorize filing and how an amendment or abandonment will be handled if a required consent is not obtained. A manager's signature on the state filing does not replace the necessary member action. Keep the written approval with the exact merger agreement and survivor operating agreement that the members reviewed, especially where distribution rights change.
- Missouri's LLC public filing is a Notice of Merger. Section 347.129 requires that document, rather than a generically labeled Articles of Merger. The notice identifies the constituent LLCs and jurisdictions, the survivor, the required approval information, and where the merger agreement can be obtained. It also addresses the effective date, which may be delayed up to 90 days under the statute, and the applicable service information. Coordinate those details with the destination filing and preserve accepted copies. The Secretary of State's fee schedule lists a $25 fee for an LLC merger with an LLC survivor, separate from destination formation and merger charges.
- The LLC merger's effects appear in section 347.133. The effect statute provides for the survivor's succession to property and liabilities and preserves creditor rights and pending proceedings. The nonsurviving Missouri LLC ceases its separate existence and its articles are canceled through the merger process. A separate pre-merger liquidation should not be assumed necessary. However, a newly formed destination survivor does not automatically acquire the Missouri LLC's original formation date merely because it succeeds to its business. The federal tax treatment and EIN consequences of the actual merger should be determined before closing, rather than promised as universal attributes of every interstate LLC merger.
- Missouri added express LLC good-standing certificate provisions effective August 28, 2026. Section 347.044 specifies the contents and evidentiary effect of certificates for domestic and foreign LLCs, including individual series. The change is relevant where Texas or a lender requires current status evidence. It does not create a general same-type outbound LLC conversion procedure. Missouri LLCs generally do not file routine annual registration reports, while corporations do, as explained in the Secretary of State's business FAQs. Check the correct entity's status and any corporate reporting arrears. A certificate is not a substitute for resolving the actual tax or contractual conditions of closing.
- Confirm corporate conversion charges and third-party consent requirements for the chosen structure. The general fee schedule does not separately label every outbound corporate conversion filing, so obtain the applicable classification before submitting payment and identify any additional service charge separately. Destination and professional charges remain separate. Review financing agreements for express conversion or merger restrictions, and determine required licensing and insurance updates. An LLC merger into a new survivor can trigger contract language different from a direct corporate conversion. Required consents should identify the actual survivor or converted entity and be obtained before the coordinated effective time.
- Missouri's capital-gain subtraction requires a transaction-specific tax analysis. Section 143.121 permits individuals to subtract federally reported capital-gain income for tax years beginning January 1, 2025. The general corporate subtraction has a separate future individual-rate trigger, so it should not be assumed available merely because a corporation moves during 2026. A state subtraction also does not establish that a conversion or merger is federally tax-free. Identify whether the relevant gain belongs to an individual owner or the entity and whether it is capital gain or ordinary-income recapture. The Department of Revenue's capital-gain guidance addresses the entity-level limitations.
- Complete the continuing registrations and preserve the accepted closing evidence. If the Texas entity retains Missouri operations, evaluate foreign qualification and registered-agent duties, together with continuing tax accounts. The statutory service consent for historical claims is not ordinary permission to transact ongoing business. Mark a return final only when that taxpayer's filing obligation ends. Retain the approved conversion or merger documents, owner approvals, and accepted filings from both states, with required status evidence and third-party consents. Record the effective time and assign the first destination report. Any continuing Missouri corporate registration report or foreign-entity obligation should remain on the compliance calendar after the move.
