
Change the state. Keep the company.
Move your LLC out of Arizona via redomestication.
Start the process of transferring your LLC out of Arizona in under five minutes.
Keep your existing contracts, credit history, and EIN.
Handled by a dually licensed attorney and CPA.
100% online. Flat-fee. No sales call required.





Executive Summary
Redomestication is the legal process of transferring a company out of Arizona to Florida, maintaining the existing federal employer identification number (FEIN), contracts, bank accounts, and in most cases, LLC name.
- No Downtime: When executed by a professional, there is no operational or financial disruption.
- Complexity: This process exists at the intersection of federal tax law and the laws of Florida and Arizona. It is not a "DIY" weekend project.
- Timeline: Redomestication takes about three months from start to finish, and expedite options are available. The intake process is entirely electronic, takes less than five minutes to get started, and can be completed on our redomestication platform here.
- Credentials: All work is handled by a dually-licensed attorney and CPA.
- Pricing: Pricing varies depending on the size of the company and is flat-fee.
- Get Started: No need to "request a quote." The exact price can be seen in under 30 seconds at the above link.
Move your LLC from Arizona to Florida without turning it into a second job.
You can see the exact price in under 30 seconds, complete the online intake in less than five minutes, and receive the documents for e-signature within 48 hours.
Seven answers you should demand before hiring anyone to redomesticate your LLC.
A redomestication from Arizona to Florida should not begin with uncertainty about price, timing, responsibility, or what happens if the filing encounters a problem.
| Ask this before you hire anyone | Cummings & Cummings Law | Any other provider |
|---|---|---|
| Can I see my exact price before I engage you? |
Yes. See the exact price online in about 30 seconds.
|
Often requires a sales call. Ask for the complete price in writing before you provide payment information. |
| How much of my time will the intake require? |
Less than five minutes for the online intake in a typical matter.
|
Ask whether calls, meetings, questionnaires, or manual document exchanges are required. |
| When will my legal documents be prepared? |
Within 48 hours after engagement and receipt of the required information. Faster if you choose to expedite.
|
Sometimes weeks. Ask for a specific preparation deadline, not an open-ended estimate. |
| Who actually prepares the legal work? |
Prof. Chad D. Cummings, CPA, Esq., M.S.T., LL.M., CMA, CFE, CIA, CRMA, CISA, CITP, FCPA, PFS, CFP personally prepares every document.
|
Confirm the name and credentials of the professional. Will it be an attorney, CPA, intern, paralegal? Where are they based? |
| Who submits and manages the state filings? |
We submit the required filings in Arizona and Florida and address
filing-office inquiries during the process.
|
Confirm whether the provider files both sides of the transaction or leaves part of the process to you. |
| Will I receive status updates while the states review the filings? |
Yes. We provide weekly status updates via email every Friday at no additional charge.
|
Many firms only provide updates upon request. Ask how often you will receive an update and whether updates cost extra. |
| What happens if the redomestication cannot be completed? |
We will refund your filing costs and 120% of the legal fees you paid if we are unable to obtain the approval of the Department of State.
|
Ask for the provider's remedy in writing before you engage the provider. Check their credentials and track record with the state bar, BBB, and Google Reviews. |
Redomestication changes where your LLC is domiciled, not the identity of the business itself.
When handled by a professional, the same legal entity continues uninterrupted from Arizona to Florida with no operational or financial disruption.
- Existing legal entity
- Existing FEIN
- Existing contracts
- Existing bank accounts
- Existing credit history
- Existing business history
- Same legal entity
- Same FEIN
- Same contracts
- Same bank accounts
- Same credit history
- Same business history
You provide the information and signatures. We take it from there.
Our engagement is designed for one task: changing the domicile of your LLC from Arizona to Florida while preserving the company's continuity.
If our redomestication process does not fit your LLC, we will tell you.
If the information you provide shows that our redomestication service cannot be used to move your LLC from Arizona to Florida, we will refund all of your costs and fees and inform you promptly before any instruments are filed. We will not waste your time or money.
In this circumstance, we will also suggest alternatives to explore with your tax professional, including referrals, where appropriate.
Your Redomestication Closing and Tax Continuity Packet.
After the redomestication from Arizona to Florida is complete, we deliver the closing materials and practical next-step instructions for you and your tax professional.
How to transfer your company to Florida and keep the EIN with zero downtime [step-by-step]
How to move a corporation from Illinois to Florida [step-by-step process]
How to transfer an Illinois LLC to Florida and keep the EIN [step-by-step]
Attorney and CPA: How to transfer a corporation to Florida from Georgia [step-by-step]
Attorney and CPA: How to move an LLC from Georgia to Florida [step-by-step]
How to transfer a corporation out of New York to Florida [step-by-step]
How to transfer an LLC out of New York to Florida [step-by-step]
Steps to transfer a company (LLC or corporation) to Florida
Report: Billionaire Stephen Ross says South Florida’s business relocation push in the '1st inning'
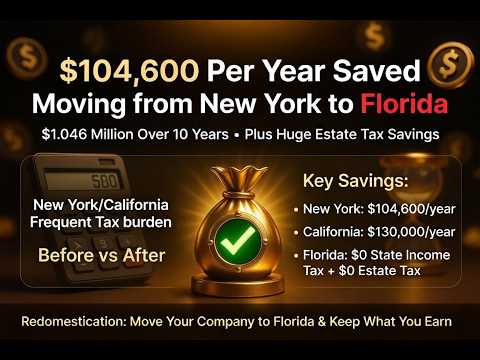
Report: How Much Americans Save on Taxes by Moving to Florida
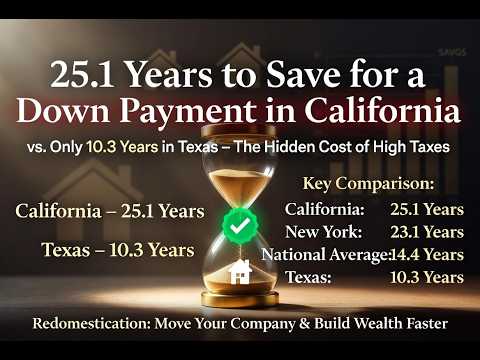
Report: Years to Save for a Home by State and Why Business Owners Are Moving to Texas and Florida
Report: Why Are So Many Companies Moving to Florida?
How to transfer your company to Florida and keep the EIN with zero downtime [step-by-step]
How to move a corporation from Illinois to Florida [step-by-step process]
How to transfer an Illinois LLC to Florida and keep the EIN [step-by-step]
Attorney and CPA: How to transfer a corporation to Florida from Georgia [step-by-step]
Attorney and CPA: How to move an LLC from Georgia to Florida [step-by-step]
How to transfer a corporation out of New York to Florida [step-by-step]
How to transfer an LLC out of New York to Florida [step-by-step]
Steps to transfer a company (LLC or corporation) to Florida
Report: Billionaire Stephen Ross says South Florida’s business relocation push in the '1st inning'
Report: How Much Americans Save on Taxes by Moving to Florida
Report: Years to Save for a Home by State and Why Business Owners Are Moving to Texas and Florida
Report: Why Are So Many Companies Moving to Florida?
Redomestication, also known as redomesticating, refers to the lesser-known legal process of transferring or moving the "home state" of an existing corporation, partnership, or LLC to a new state. It means keeping your existing company name, credit, and federal employer identification number (FEIN) without wasting time and money creating a new business entity, applying for foreign registration, or moving assets between companies.
— Prof. Chad D. Cummings, CPA, Esq., M.S.T., LL.M., CMA, CFE, CIA, CRMA, CISA, CITP, FCPA, PFS, CFP
Florida destination-state requirements
A redomestication of an LLC into Florida is governed by Fla. Stat. §§ 605.1041-605.1046 together with the law of Arizona. The transaction requires an approved Plan of Conversion, Articles of Conversion, and the applicable Florida organizational filing. The Florida filing must be coordinated with the Arizona outbound instrument so the same LLC continues without interruption.
Tax considerations when moving a LLC from Arizona to Florida
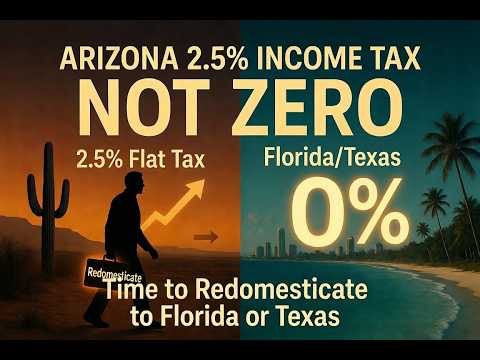
Arizona has a flat 2.5% individual income tax and a 4.9% corporate income tax. An LLC is not automatically taxed as a corporation: its federal classification and elections determine whether ordinary income passes through to owners. Eligible partnerships and S corporations can elect Arizona's pass-through entity tax; the 2026 estimated-tax worksheet uses a 2.5% rate. The owner credit and resident or nonresident filing position should be modeled before moving your LLC from Arizona to Florida.
Arizona's principal consumption tax is the transaction privilege tax, or TPT, imposed on businesses' taxable receipts under specified classifications. It is commonly passed through to customers, but it is not simply a tax imposed directly on every buyer. The state retail rate is 5.6%; county and city taxes can materially increase the total. Use the current TPT rate tables for the business location and activity instead of a statewide average.
Recent local changes can affect relocation comparisons. Phoenix increased its city TPT rate for most classifications from 2.3% to 2.8% on July 1, 2025, according to the city's rate notice. Separately, Arizona ended municipal TPT on qualifying residential rentals beginning January 1, 2025; transient lodging remains a different classification. Arizona does not impose a separate estate or inheritance tax.
A domestication does not remove TPT obligations for continuing Arizona sales or income-tax obligations for Arizona-source income. Review payroll and local licensing accounts, along with any property remaining in the state. An owner's change of residence must be established separately from the company's new formation state.
For rental businesses, distinguish residential occupancy from short-term lodging when reviewing the 2025 repeal. The company's formation state does not determine which Arizona rental classification applies to a property or its receipts.
Florida imposes no individual income tax. A qualifying Florida resident therefore does not pay Florida income tax on wages, investment income, or ordinary pass-through business income. The state generally taxes C corporation income at 5.50 percent after Florida adjustments, apportionment, and the $50,000 exemption. An LLC classified as a corporation follows the corporate rules; an LLC's legal label alone does not determine its tax treatment. S corporations can have Florida corporate-tax obligations on certain federally taxable built-in gains or excess net passive income. A partnership or LLC taxed as a partnership can also have a Florida Form F-1065 filing obligation when it has a corporate owner; pass-through treatment does not make every information return unnecessary. The Florida Income Tax Code explains classification and filing requirements.
Florida's general sales tax is 6.00 percent, with county surtaxes where applicable. Effective October 1, 2025, Florida repealed sales tax and the related discretionary surtax on commercial real-property rentals. The enacted 2025 repeal provision in section 37 of H.B. 7031 establishes the effective date. Transient accommodations, parking, and other separately taxable rental transactions require their own analysis. Florida has no current separate estate or inheritance tax, but moving a business does not itself establish an owner's Florida domicile or entitlement to homestead benefits.
Redomesticating a LLC from Arizona to Florida can reduce the costs of maintaining a company under a state law that no longer matches its operations. Tax savings depend on the owners' residence, tax classification, and where the business actually earns income. Employees, property, inventory, or other business activity remaining in Arizona can preserve its income-tax, sales-tax, payroll, or registration obligations. Complete any required final returns before closing accounts.
Economic nexus also matters for an out-of-state seller without a physical office. South Dakota v. Wayfair, Inc., 585 U.S. 162 (2018), rejected the physical-presence prerequisite for sales-tax collection. A different, limited protection applies to certain solicitation of orders for tangible personal property under 15 U.S.C. § 381. Wisconsin Department of Revenue v. William Wrigley, Jr., Co., 505 U.S. 214 (1992), addresses that net-income-tax protection. It is not a general exemption from sales taxes or taxes on services. A state-by-state nexus review should identify each tax, applicable threshold, protected activity, and continuing filing duty.
Specific legal requirements to transfer a LLC to Florida from Arizona
Arizona has state-specific statutory, approval, filing, fee, and sequencing requirements that must be coordinated with Florida law. The requirements below are the origin-state requirements applicable to this transaction.
- Arizona allows a corporation or LLC to domesticate into another state while retaining its entity type. A.R.S. § 29-2501 authorizes an Arizona domestic entity to become a domestic entity of the same type under another jurisdiction's law if the destination permits it. For example, an Arizona LLC can become a Florida LLC without treating the transaction as the formation of an unrelated business. A simultaneous change from LLC to corporation follows the separate conversion provisions. For Arizona corporations and LLCs, the filing office is the Arizona Corporation Commission, not the Secretary of State. Confirm the destination route before approving your LLC's plan.
- Create a complete written Plan of Domestication. A.R.S. § 29-2502 requires the entity's current identity and the resulting name and jurisdiction, together with the manner in which interests will be converted. Include the proposed public formation document and the full text of the private governing rules to be recorded. An LLC should reconcile the destination operating agreement with its existing membership ledger, including voting rights and management authority. A corporation should reconcile its charter and bylaws with the outstanding share classes. State any consideration or changed economic rights precisely so owners can approve the actual transaction instead of an incomplete description.
- Approval follows a statutory hierarchy. Under A.R.S. § 29-2503, first apply the governing law and organizational documents addressing domestication. Where they do not provide an applicable rule, review the rule for a merger with an unaffiliated entity and the statute's fallback approval requirement. The law also protects an owner who would incur personal liability after the transaction, subject to its specified prior-consent exception. Do not assume that one manager's signature on the public form proves member approval or that a corporate board can dispense with a required shareholder vote. Retain the applicable provision and the signed approval in the closing record.
- File the Statement of Domestication on the correct basis. The Commission publishes Form M090, Statement of Domestication, with separate options for an entity entering Arizona, an entity leaving but registering as foreign, and an entity leaving without Arizona registration. An outbound Arizona LLC becoming a foreign LLC should select the option matching its post-closing Arizona activity. If it will continue doing business in Arizona, the form calls for the appropriate foreign registration attachment. If it will not register, provide the mailing address required for service of process. Keep the domesticating and domesticated entity names in their correct fields.
- The statute allows a statement or a qualifying plan. A.R.S. § 29-2505 specifies the statement's contents and permits a signed plan satisfying those requirements to be filed instead. The internal plan is therefore not invariably required to be filed, but neither is it categorically prohibited from filing. The shorter statement often avoids publishing detailed ownership terms unnecessarily. Reconcile the approval recital with the actual member or shareholder action, and include the required information for the destination entity. A domestic formation attachment is appropriate for an entity becoming Arizona domestic; it should not be added reflexively to a transaction leaving the state.
- Coordinate effectiveness and signatures. A delayed effective date under § 29-2505 may not be more than 90 days after filing. Match the destination's permitted timing and specify a time zone when the documents use an effective time. The M090 instructions identify the proper signer: a corporate officer or board chair, a manager for a manager-managed LLC, or a member for a member-managed LLC. Include the title and complete the verification. Signing authority, internal approval, and the effective date are separate questions; a correct signature does not cure an unapproved plan.
- Confirm fees and current filing methods with the Commission. The Arizona Corporation Commission Corporations Division provides the current filing system and fee instructions. The total can differ when the transaction also requires foreign registration or expedited processing. Obtain a filing-specific amount before payment instead of treating an unverified service-provider package price as a state charge. Bring the public record current and resolve any administrative dissolution or other status problem that interferes with the transaction. Arizona corporations file annual reports, while Arizona LLCs do not have an annual-report requirement merely because they are LLCs. Other tax and licensing renewals remain separate.
- Use the March 2026 LLC fee schedule for the actual charge. The current Commission LLC schedule lists $50 for a Statement of Domestication and $85 with standard expedited processing. A foreign LLC registration is a separate $150 regular filing when needed. The Commission now identifies its online service as Arizona Business Center, or ABC, formerly eCorp. Use the current fee and payment guidance to avoid relying on obsolete portal instructions. The corporate schedule must be used for a corporation; LLC charges should not be assumed to apply to both forms.
- Plan for a change or failed closing. A.R.S. § 29-2504 governs amendment and abandonment. The plan can authorize a procedure, but material changes affecting an owner's consideration or governance rights can require renewed approval. If a filed domestication has a future effective date and is abandoned, deliver the required abandonment filing before the scheduled effectiveness. The closing instructions should identify who may authorize a correction, who will confirm the destination acceptance, and who will stop the Arizona filing if a closing condition fails. Preserve the final approved version so the signed forms do not inadvertently reflect an earlier draft.
- Continuity preserves obligations as well as assets. Under A.R.S. § 29-2506, the domesticated entity continues without interruption, retains property, and remains liable for existing obligations. Pending proceedings are not erased by the move. When the resulting foreign entity is not registered in Arizona, the law preserves a means of service for enforceable liabilities. Use a monitored service address and update it as required. Review contracts for language covering domestication, change of jurisdiction, or notice to a lender. Statutory continuity is useful evidence for a bank or title company, but it does not rewrite contractual requirements or guarantee that every governmental license continues unchanged.
- Complete the ownership and operational records. Update the operating agreement or bylaws at the approved effective time and reconcile the ownership ledger with the plan. Review the company's name on insurance, real-estate records, and financing documents. Where a lender requires consent or a secured-party filing changes because the debtor's jurisdiction changes, coordinate that work with the lender before closing. Determine whether a federal tax election or EIN is affected by the actual transaction rather than assuming that state-law continuity answers the federal question. Retain the accepted Arizona and Florida documents together so third parties can trace the same entity across the move.
- Close Arizona accounts only where obligations actually end. If your LLC continues Arizona business after moving from Arizona to Florida, maintain the necessary foreign registration and statutory agent. Continuing Arizona receipts can preserve transaction privilege tax obligations even when the business no longer has an Arizona charter. Review income-tax, payroll, and local-license accounts separately, and distinguish final returns from continuing filings. The permanent file should include the approved plan, acceptance evidence, remaining consent requirements, and responsibility for post-closing notices. Calendar the destination's first reporting deadline and any Arizona corporate annual report that remains due.
