
Change the state. Keep the company.
Move your LLC out of Georgia via redomestication.
Start the process of transferring your LLC out of Georgia in under five minutes.
Keep your existing contracts, credit history, and EIN.
Handled by a dually licensed attorney and CPA.
100% online. Flat-fee. No sales call required.





Executive Summary
Redomestication is the legal process of transferring a company out of Georgia to Florida, maintaining the existing federal employer identification number (FEIN), contracts, bank accounts, and in most cases, LLC name.
- No Downtime: When executed by a professional, there is no operational or financial disruption.
- Complexity: This process exists at the intersection of federal tax law and the laws of Florida and Georgia. It is not a "DIY" weekend project.
- Timeline: Redomestication takes about three months from start to finish, and expedite options are available. The intake process is entirely electronic, takes less than five minutes to get started, and can be completed on our redomestication platform here.
- Credentials: All work is handled by a dually-licensed attorney and CPA.
- Pricing: Pricing varies depending on the size of the company and is flat-fee.
- Get Started: No need to "request a quote." The exact price can be seen in under 30 seconds at the above link.
Move your LLC from Georgia to Florida without turning it into a second job.
You can see the exact price in under 30 seconds, complete the online intake in less than five minutes, and receive the documents for e-signature within 48 hours.
Seven answers you should demand before hiring anyone to redomesticate your LLC.
A redomestication from Georgia to Florida should not begin with uncertainty about price, timing, responsibility, or what happens if the filing encounters a problem.
| Ask this before you hire anyone | Cummings & Cummings Law | Any other provider |
|---|---|---|
| Can I see my exact price before I engage you? |
Yes. See the exact price online in about 30 seconds.
|
Often requires a sales call. Ask for the complete price in writing before you provide payment information. |
| How much of my time will the intake require? |
Less than five minutes for the online intake in a typical matter.
|
Ask whether calls, meetings, questionnaires, or manual document exchanges are required. |
| When will my legal documents be prepared? |
Within 48 hours after engagement and receipt of the required information. Faster if you choose to expedite.
|
Sometimes weeks. Ask for a specific preparation deadline, not an open-ended estimate. |
| Who actually prepares the legal work? |
Prof. Chad D. Cummings, CPA, Esq., M.S.T., LL.M., CMA, CFE, CIA, CRMA, CISA, CITP, FCPA, PFS, CFP personally prepares every document.
|
Confirm the name and credentials of the professional. Will it be an attorney, CPA, intern, paralegal? Where are they based? |
| Who submits and manages the state filings? |
We submit the required filings in Georgia and Florida and address
filing-office inquiries during the process.
|
Confirm whether the provider files both sides of the transaction or leaves part of the process to you. |
| Will I receive status updates while the states review the filings? |
Yes. We provide weekly status updates via email every Friday at no additional charge.
|
Many firms only provide updates upon request. Ask how often you will receive an update and whether updates cost extra. |
| What happens if the redomestication cannot be completed? |
We will refund your filing costs and 120% of the legal fees you paid if we are unable to obtain the approval of the Department of State.
|
Ask for the provider's remedy in writing before you engage the provider. Check their credentials and track record with the state bar, BBB, and Google Reviews. |
Redomestication changes where your LLC is domiciled, not the identity of the business itself.
When handled by a professional, the same legal entity continues uninterrupted from Georgia to Florida with no operational or financial disruption.
- Existing legal entity
- Existing FEIN
- Existing contracts
- Existing bank accounts
- Existing credit history
- Existing business history
- Same legal entity
- Same FEIN
- Same contracts
- Same bank accounts
- Same credit history
- Same business history
You provide the information and signatures. We take it from there.
Our engagement is designed for one task: changing the domicile of your LLC from Georgia to Florida while preserving the company's continuity.
If our redomestication process does not fit your LLC, we will tell you.
If the information you provide shows that our redomestication service cannot be used to move your LLC from Georgia to Florida, we will refund all of your costs and fees and inform you promptly before any instruments are filed. We will not waste your time or money.
In this circumstance, we will also suggest alternatives to explore with your tax professional, including referrals, where appropriate.
Your Redomestication Closing and Tax Continuity Packet.
After the redomestication from Georgia to Florida is complete, we deliver the closing materials and practical next-step instructions for you and your tax professional.
How to transfer your company to Florida and keep the EIN with zero downtime [step-by-step]
How to move a corporation from Illinois to Florida [step-by-step process]
How to transfer an Illinois LLC to Florida and keep the EIN [step-by-step]
Attorney and CPA: How to transfer a corporation to Florida from Georgia [step-by-step]
Attorney and CPA: How to move an LLC from Georgia to Florida [step-by-step]
How to transfer a corporation out of New York to Florida [step-by-step]
How to transfer an LLC out of New York to Florida [step-by-step]
Steps to transfer a company (LLC or corporation) to Florida
Report: Billionaire Stephen Ross says South Florida’s business relocation push in the '1st inning'
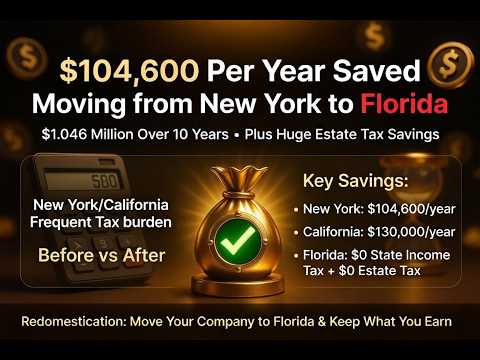
Report: How Much Americans Save on Taxes by Moving to Florida
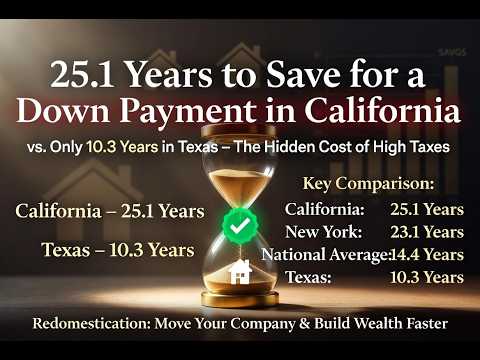
Report: Years to Save for a Home by State and Why Business Owners Are Moving to Texas and Florida
Report: Why Are So Many Companies Moving to Florida?
How to transfer your company to Florida and keep the EIN with zero downtime [step-by-step]
How to move a corporation from Illinois to Florida [step-by-step process]
How to transfer an Illinois LLC to Florida and keep the EIN [step-by-step]
Attorney and CPA: How to transfer a corporation to Florida from Georgia [step-by-step]
Attorney and CPA: How to move an LLC from Georgia to Florida [step-by-step]
How to transfer a corporation out of New York to Florida [step-by-step]
How to transfer an LLC out of New York to Florida [step-by-step]
Steps to transfer a company (LLC or corporation) to Florida
Report: Billionaire Stephen Ross says South Florida’s business relocation push in the '1st inning'
Report: How Much Americans Save on Taxes by Moving to Florida
Report: Years to Save for a Home by State and Why Business Owners Are Moving to Texas and Florida
Report: Why Are So Many Companies Moving to Florida?
Redomestication, also known as redomesticating, refers to the lesser-known legal process of transferring or moving the "home state" of an existing corporation, partnership, or LLC to a new state. It means keeping your existing company name, credit, and federal employer identification number (FEIN) without wasting time and money creating a new business entity, applying for foreign registration, or moving assets between companies.
— Prof. Chad D. Cummings, CPA, Esq., M.S.T., LL.M., CMA, CFE, CIA, CRMA, CISA, CITP, FCPA, PFS, CFP
Florida destination-state requirements
A redomestication of an LLC into Florida is governed by Fla. Stat. §§ 605.1041-605.1046 together with the law of Georgia. The transaction requires an approved Plan of Conversion, Articles of Conversion, and the applicable Florida organizational filing. The Florida filing must be coordinated with the Georgia outbound instrument so the same LLC continues without interruption.
Tax considerations when moving a LLC from Georgia to Florida
Georgia reduced both its individual and corporate income-tax rate to 4.99% for tax years beginning on or after January 1, 2026. The reduction is retroactive under House Bill 463, signed May 11, 2026; the Department of Revenue's important tax updates supersede older descriptions using 5.19%. The enacted legislation also schedules further individual-rate reductions of 0.125 percentage point annually beginning in 2027, subject to revenue conditions, toward 3.99%. Future reductions should not be treated as unconditional current rates.
An LLC's tax treatment depends on its federal classification and elections. Ordinary income from a partnership or S corporation generally passes through to owners, but eligible entities can elect Georgia's entity-level pass-through tax. Compare the election and corresponding owner treatment before moving your LLC from Georgia to Florida. Georgia-source income can remain taxable after an owner becomes a nonresident, and changing the charter does not itself establish a change in personal residence.
Georgia's state sales tax is 4%, with county and other local taxes added to covered transactions. The Department's sales-tax rate tables should be checked for the exact county and effective date. Local rates can change quarterly, so a statewide combined-rate average is not a reliable estimate for a particular store, warehouse, or delivery location. Local property taxes and business occupational taxes also depend on where the business operates.
Georgia has no separate estate or inheritance tax. For an outbound conversion, reconcile any remaining income-tax and payroll obligations and identify whether taxable Georgia sales will continue. Foreign registration can preserve the company's authority to operate after conversion, but it does not replace tax registration. Close accounts only when the relevant activity ends, and preserve the accepted conversion documents with the final or continuing tax returns.
House Bill 463 also increased the 2026 standard deduction to $15,000 for single filers and $30,000 for married couples filing jointly.
Florida imposes no individual income tax. A qualifying Florida resident therefore does not pay Florida income tax on wages, investment income, or ordinary pass-through business income. The state generally taxes C corporation income at 5.50 percent after Florida adjustments, apportionment, and the $50,000 exemption. An LLC classified as a corporation follows the corporate rules; an LLC's legal label alone does not determine its tax treatment. S corporations can have Florida corporate-tax obligations on certain federally taxable built-in gains or excess net passive income. A partnership or LLC taxed as a partnership can also have a Florida Form F-1065 filing obligation when it has a corporate owner; pass-through treatment does not make every information return unnecessary. The Florida Income Tax Code explains classification and filing requirements.
Florida's general sales tax is 6.00 percent, with county surtaxes where applicable. Effective October 1, 2025, Florida repealed sales tax and the related discretionary surtax on commercial real-property rentals. The enacted 2025 repeal provision in section 37 of H.B. 7031 establishes the effective date. Transient accommodations, parking, and other separately taxable rental transactions require their own analysis. Florida has no current separate estate or inheritance tax, but moving a business does not itself establish an owner's Florida domicile or entitlement to homestead benefits.
Redomesticating a LLC from Georgia to Florida can reduce the costs of maintaining a company under a state law that no longer matches its operations. Tax savings depend on the owners' residence, tax classification, and where the business actually earns income. Employees, property, inventory, or other business activity remaining in Georgia can preserve its income-tax, sales-tax, payroll, or registration obligations. Complete any required final returns before closing accounts.
Economic nexus also matters for an out-of-state seller without a physical office. South Dakota v. Wayfair, Inc., 585 U.S. 162 (2018), rejected the physical-presence prerequisite for sales-tax collection. A different, limited protection applies to certain solicitation of orders for tangible personal property under 15 U.S.C. § 381. Wisconsin Department of Revenue v. William Wrigley, Jr., Co., 505 U.S. 214 (1992), addresses that net-income-tax protection. It is not a general exemption from sales taxes or taxes on services. A state-by-state nexus review should identify each tax, applicable threshold, protected activity, and continuing filing duty.
Specific legal requirements to transfer a LLC to Florida from Georgia
Georgia has state-specific statutory, approval, filing, fee, and sequencing requirements that must be coordinated with Florida law. The requirements below are the origin-state requirements applicable to this transaction.
- Georgia permits an outbound conversion for an LLC or business corporation. A Georgia LLC uses O.C.G.A. § 14-11-906; a Georgia corporation uses O.C.G.A. § 14-2-1109.3. Each provision allows the listed foreign forms when the destination law permits the conversion, including a same-type LLC or corporation moving to another state. The Secretary of State's Entity Conversion Matrix, revised March 20, 2026, identifies the approved filing combinations. Section 14-2-1109.1 is not the correct outbound corporate authority. Identify the current and resulting entity type before preparing your LLC's transaction.
- Prepare a Plan of Conversion that explains the ownership treatment. Both § 14-11-906(b) and § 14-2-1109.3(b) require a plan stating the manner and basis for converting members' interests or corporate shares into the resulting entity's interests, shares, obligations, or other securities. A same-owner move should expressly identify the resulting ownership rather than leaving it to inference. Attach or incorporate the destination governing documents as appropriate to the transaction. Explain changed voting rights or management arrangements before seeking approval. Record the closing conditions and the person authorized to complete the destination and Georgia filings.
- For a Georgia LLC, examine the operating agreement before applying the default. § 14-11-906(c) requires unanimous member consent unless the articles of organization or a written operating agreement provide otherwise. A majority rule should therefore be supported by an actual qualifying provision, not assumed from ordinary management authority. Preserve the signed consents and the provision used to determine the vote. The same section's abandonment rule also looks to the plan and, where relevant, the articles or written operating agreement. Do not let a public certificate's signature substitute for the members' approval of the plan's economic and governance terms.
- A Georgia corporation's outbound vote is different. Under § 14-2-1109.3(c), the board submits and recommends the plan under the referenced procedures, and all shareholders must approve the plan. This is not the ordinary majority standard used for every other corporate action or in every other state. Include nonvoting or otherwise specially situated holders in the legal review instead of assuming that only the largest voting block matters. The statute also limits post-approval amendments that adversely change consideration or other material terms without the relevant authorization. Retain the board action and shareholder approvals with the complete plan.
- The Georgia public instrument is a Certificate of Conversion. The required contents appear in § 14-11-906(g) for LLCs and § 14-2-1109.3(i) for corporations. Identify the current Georgia name, the resulting name and jurisdiction, and any later effective date and time. Include the appropriate approval recital and the service-of-process statements. The Secretary of State's Business Division FAQ explains filing procedures for conversion documents. Prepare a certificate meeting the statute rather than assuming that an inbound articles-of-organization form or a document labeled articles of conversion is the required Georgia outbound record.
- Include the continuing service appointment and mailing address. The outbound certificate revokes the Georgia registered agent's authority at the conversion's effective time and irrevocably appoints the Secretary of State for specified pre-conversion obligations. It must provide a mailing address for process and state that the Secretary of State will be notified of address changes. The LLC provisions also preserve applicable dissenting-member claims. Use an address that will remain monitored after the Georgia office closes. If the resulting foreign entity will continue Georgia business, its separate foreign registration and agent arrangement must be coordinated with this statutory service provision.
- Use the current fee breakdown. The 2026 Entity Conversion Matrix lists a $105 conversion charge, consisting of a $95 filing fee and a $10 service charge. If the resulting entity must register to continue Georgia business, the matrix identifies an additional $225 foreign-registration charge. The combined $330 amount is therefore not the base fee for every outbound conversion. Destination filing and optional expedited services are additional. Confirm the exact filing combination and payment method before submission, and preserve the accepted certificate. A payment confirmation or an uploaded draft does not by itself establish that the conversion was approved for filing.
- Destination law supplies an essential part of the legal effect. Both § 14-11-906(e) and § 14-2-1109.3(g) provide that the conversion is effected, and has the effects provided, under the law of the resulting entity's jurisdiction and the plan to the extent consistent with that law. Identify the destination continuity provision in the closing memorandum. Do not cite the Georgia LLC statute as if it were a universal corporate vesting rule. Reconcile names and effective times across both filings and obtain any certified evidence required to complete the Georgia record or demonstrate the resulting entity's existence.
- A filed corporate conversion may need a separate amendment certificate. § 14-2-1109.3(d) requires a Certificate of Amendment of Conversion if the approved plan is amended after the original certificate is filed but before the conversion becomes effective. An officer or other authorized representative executes that filing, which must be delivered before effectiveness. Review whether the proposed change adversely affects shareholders and whether the original approval authorized it. Preserve the amended plan and shareholder action with the public amendment. A private revised plan alone does not update a public certificate that is already scheduled to take effect.
- Georgia provides a specific real-estate recording option. Under § 14-11-906(i) for LLCs and § 14-2-1109.3(k) for corporations, a certified conversion certificate can be recorded with the superior-court clerk in a county where the converting entity owns real property. The converting entity is indexed as grantor and the resulting foreign entity as grantee, and the statute exempts that certificate's recording from the specified real-estate transfer tax. Coordinate the filing with the title company and lender. This option documents the entity transition; it does not excuse a contractual consent or resolve every separate property-tax consequence.
- Keep the existing Georgia record current until closing. Georgia entities generally file annual registration between January 1 and April 1. Resolve overdue registrations and confirm the current officers or managers and registered-agent information before presenting the transaction for filing. If Florida requires a certificate of existence, obtain one meeting its timing requirements. Review loan documents, leases, and regulated licenses for notice or consent to the jurisdiction change. Federal EIN and tax-election questions depend on the particular transaction and should be considered separately, especially where the plan changes entity type or ownership in addition to changing the formation state.
- The corporate process provision requires more than a forwarding address. Under § 14-2-1109.3(j), a party serving the Secretary of State in the specified proceeding must also mail process to the resulting entity's chief executive officer, chief financial officer, secretary, or comparable officer at the listed address. Keep those records accurate after the move and ensure that the recipient can identify notices relating to the former Georgia corporation. This continuing service arrangement supports enforcement of earlier obligations even though the company's original Georgia registered-agent appointment has ended.
- Complete the continuing-business and tax follow-up. If your LLC will continue Georgia business after moving from Georgia to Florida, obtain the required foreign authority under the statute and maintain the applicable Georgia annual-registration calendar. Continuing Georgia-source income or employees can also require further tax and payroll filings. If activity ends, coordinate final returns and account closure with the actual cessation date. Retain the signed plan, all necessary approvals, accepted Georgia and destination records, real-estate recording evidence, and tax correspondence. Assign responsibility for monitoring the process address and completing the first report or renewal required in Florida.
