
Change the state. Keep the company.
Move your corporation out of Vermont via redomestication.
Start the process of transferring your corporation out of Vermont in under five minutes.
Keep your existing contracts, credit history, and EIN.
Handled by a dually licensed attorney and CPA.
100% online. Flat-fee. No sales call required.





Executive Summary
Redomestication is the legal process of transferring a company out of Vermont to Texas, maintaining the existing federal employer identification number (FEIN), contracts, bank accounts, and in most cases, corporation name.
- No Downtime: When executed by a professional, there is no operational or financial disruption.
- Complexity: This process exists at the intersection of federal tax law and the laws of Texas and Vermont. It is not a "DIY" weekend project.
- Timeline: Redomestication takes about three months from start to finish, and expedite options are available. The intake process is entirely electronic, takes less than five minutes to get started, and can be completed on our redomestication platform here.
- Credentials: All work is handled by a dually-licensed attorney and CPA.
- Pricing: Pricing varies depending on the size of the company and is flat-fee.
- Get Started: No need to "request a quote." The exact price can be seen in under 30 seconds at the above link.
Move your corporation from Vermont to Texas without turning it into a second job.
You can see the exact price in under 30 seconds, complete the online intake in less than five minutes, and receive the documents for e-signature within 48 hours.
Seven answers you should demand before hiring anyone to redomesticate your corporation.
A redomestication from Vermont to Texas should not begin with uncertainty about price, timing, responsibility, or what happens if the filing encounters a problem.
| Ask this before you hire anyone | Cummings & Cummings Law | Any other provider |
|---|---|---|
| Can I see my exact price before I engage you? |
Yes. See the exact price online in about 30 seconds.
|
Often requires a sales call. Ask for the complete price in writing before you provide payment information. |
| How much of my time will the intake require? |
Less than five minutes for the online intake in a typical matter.
|
Ask whether calls, meetings, questionnaires, or manual document exchanges are required. |
| When will my legal documents be prepared? |
Within 48 hours after engagement and receipt of the required information. Faster if you choose to expedite.
|
Sometimes weeks. Ask for a specific preparation deadline, not an open-ended estimate. |
| Who actually prepares the legal work? |
Prof. Chad D. Cummings, CPA, Esq., M.S.T., LL.M., CMA, CFE, CIA, CRMA, CISA, CITP, FCPA, PFS, CFP personally prepares every document.
|
Confirm the name and credentials of the professional. Will it be an attorney, CPA, intern, paralegal? Where are they based? |
| Who submits and manages the state filings? |
We submit the required filings in Vermont and Texas and address
filing-office inquiries during the process.
|
Confirm whether the provider files both sides of the transaction or leaves part of the process to you. |
| Will I receive status updates while the states review the filings? |
Yes. We provide weekly status updates via email every Friday at no additional charge.
|
Many firms only provide updates upon request. Ask how often you will receive an update and whether updates cost extra. |
| What happens if the redomestication cannot be completed? |
We will refund your filing costs and 120% of the legal fees you paid if we are unable to obtain the approval of the Secretary of State.
|
Ask for the provider's remedy in writing before you engage the provider. Check their credentials and track record with the state bar, BBB, and Google Reviews. |
Redomestication changes where your corporation is domiciled, not the identity of the business itself.
When handled by a professional, the same legal entity continues uninterrupted from Vermont to Texas with no operational or financial disruption.
- Existing legal entity
- Existing FEIN
- Existing contracts
- Existing bank accounts
- Existing credit history
- Existing business history
- Same legal entity
- Same FEIN
- Same contracts
- Same bank accounts
- Same credit history
- Same business history
You provide the information and signatures. We take it from there.
Our engagement is designed for one task: changing the domicile of your corporation from Vermont to Texas while preserving the company's continuity.
If our redomestication process does not fit your corporation, we will tell you.
If the information you provide shows that our redomestication service cannot be used to move your corporation from Vermont to Texas, we will refund all of your costs and fees and inform you promptly before any instruments are filed. We will not waste your time or money.
In this circumstance, we will also suggest alternatives to explore with your tax professional, including referrals, where appropriate.
Your Redomestication Closing and Tax Continuity Packet.
After the redomestication from Vermont to Texas is complete, we deliver the closing materials and practical next-step instructions for you and your tax professional.
How to transfer a company to Texas: keep the EIN with no downtime [step-by-step]
How to transfer a corporation to Texas from New York [step-by-step]
How to transfer an LLC from New York to Texas [step-by-step]
How to transfer a corporation to Texas [step-by-step]
How small business owners are transferring their LLCs to Texas [step-by-step]
How to legally move a company to Texas without starting over [step-by-step]
Transferring your business to Texas with no downtime [step-by-step]
How to transfer a corporation to Texas and keep the EIN [step-by-step]
How to transfer your LLC to Texas with no downtime [step-by-step]
How to move a company to Texas without disruption [step-by-step]

How to convert your company to Texas [step-by-step]

How to move your LLC or corporation to Texas from New York [step-by-step]
How to transfer a company to Texas: keep the EIN with no downtime [step-by-step]
How to transfer a corporation to Texas from New York [step-by-step]
How to transfer an LLC from New York to Texas [step-by-step]
How to transfer a corporation to Texas [step-by-step]
How small business owners are transferring their LLCs to Texas [step-by-step]
How to legally move a company to Texas without starting over [step-by-step]
Transferring your business to Texas with no downtime [step-by-step]
How to transfer a corporation to Texas and keep the EIN [step-by-step]
How to transfer your LLC to Texas with no downtime [step-by-step]
How to move a company to Texas without disruption [step-by-step]
How to convert your company to Texas [step-by-step]
How to move your LLC or corporation to Texas from New York [step-by-step]
Redomestication, also known as redomesticating, refers to the lesser-known legal process of transferring or moving the "home state" of an existing corporation, partnership, or LLC to a new state. It means keeping your existing company name, credit, and federal employer identification number (FEIN) without wasting time and money creating a new business entity, applying for foreign registration, or moving assets between companies.
— Prof. Chad D. Cummings, CPA, Esq., M.S.T., LL.M., CMA, CFE, CIA, CRMA, CISA, CITP, FCPA, PFS, CFP
Texas destination-state requirements
A redomestication into Texas is governed by Chapter 10, Subchapters C and D, of the Texas Business Organizations Code together with the law of Vermont. The transaction requires a written Plan of Conversion, the approvals required by the governing documents and applicable law, a Certificate of Conversion, and, for a Texas filing entity, a Certificate of Formation. The Texas filing must be coordinated with the Vermont outbound instrument so the same corporation continues without interruption.
Tax considerations when moving a corporation from Vermont to Texas
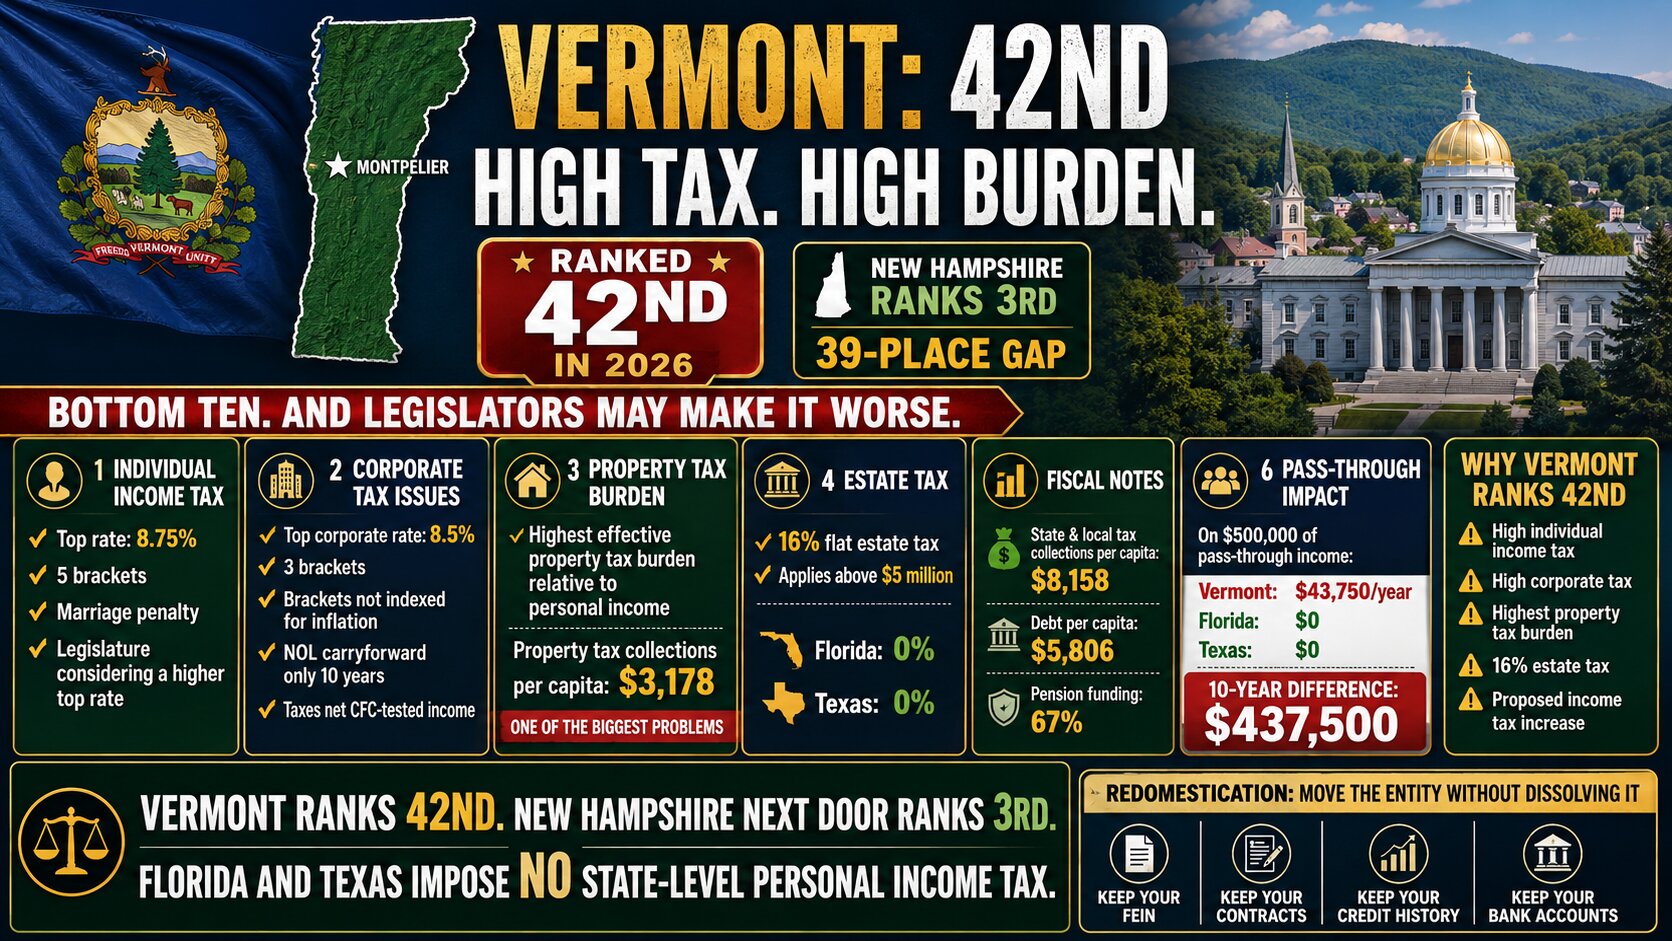
Vermont imposes graduated individual income tax with a top marginal rate of 8.75 percent. Its corporate income tax is 6.00 percent on the first $10,000 of Vermont net income, 7.00 percent on the next $15,000, and 8.50 percent above $25,000. Under 32 V.S.A. § 5832, ordinary C corporation minimum taxes depend on Vermont gross receipts, ranging from $100 to $100,000. A loss does not automatically eliminate the minimum. S corporations and partnership-classified LLCs generally pass income to owners but can owe Vermont's separate $250 annual business-entity tax, with additional nonresident-owner or composite-return obligations. A Vermont registration can itself carry minimum-tax filing consequences; compare the Secretary of State record with tax-account requirements before assuming an inactive business has no return to file.
Vermont's estate tax has a $5 million payment threshold and a 16 percent rate on the taxable amount above the applicable exclusion. In 2026, the Legislature also raised the estate-tax filing threshold to $5 million to align it with the payment threshold, subject to the separate federal-return filing trigger described in the Department of Taxes' current estate guidance. Vermont does not impose a separate inheritance tax. Changing a business's state of organization does not determine the owner's domicile or remove Vermont real estate from estate-tax review.
The general state sales tax is 6.00 percent, with a 1.00 percent local option tax where adopted. Since July 1, 2024, taxable prewritten software includes software accessed remotely, as explained in the software-tax guidance. A corporation moving from Vermont to Texas should identify continuing Vermont customers, property, payroll, and registrations. Vermont's 2026 tax legislation also changes federal conformity, so federal deductions and gains should not be assumed to receive identical Vermont treatment.
Texas imposes no individual income tax and prohibits a tax on individuals' net income under Texas Constitution article VIII, section 24-a. Texas also has no conventional corporate net income tax. Its franchise tax, however, applies to many corporations, LLCs, and other taxable entities, including businesses treated as pass-through entities for federal income-tax purposes. A federal S corporation election or partnership classification does not, by itself, exempt the business from Texas franchise-tax law.
For 2026 and 2027 report years, the franchise-tax no-tax-due threshold is $2.65 million in annualized total revenue. The general rates are 0.375 percent for qualifying retail or wholesale businesses and 0.75 percent for other businesses, applied to the taxable margin apportioned to Texas. Eligible businesses with no more than $20 million in annualized revenue can use the EZ computation at 0.331 percent, subject to its separate rules. The Texas Comptroller's franchise-tax guidance provides the current thresholds and methods. The threshold is not a deduction from taxable margin and does not establish that all income above it is taxed at the general rate. The compensation deduction limit is $480,000 per person for these report years. Compare the available margin methods using the business's actual revenue, eligible costs, compensation, and Texas apportionment before choosing a computation method.
Businesses at or below the revenue threshold generally no longer file a No Tax Due Report for report years 2024 and later, but an applicable Public Information Report or Ownership Information Report remains required. The ordinary annual deadline is May 15. Texas's state sales tax is 6.25 percent, with local taxes bringing the combined rate as high as 8.25 percent. Sales-tax, unemployment, property-tax, and licensing obligations may continue even when no franchise tax is payable. Texas has no current separate estate or inheritance tax.
Redomesticating a corporation from Vermont to Texas changes its governing jurisdiction. Actual tax savings depend on the owners' residence, the company's classification, and the location of its operations and receipts. Continuing employees, property, inventory, or qualifying sales in Vermont can preserve that state's filing and payment obligations. Do not close an account merely because the Texas conversion documents have been accepted.
South Dakota v. Wayfair, Inc., 585 U.S. 162 (2018), permits sales-tax nexus without the former physical-presence prerequisite. 15 U.S.C. § 381 instead provides limited net-income-tax protection for specified solicitation of tangible-goods orders. Wisconsin Department of Revenue v. William Wrigley, Jr., Co., 505 U.S. 214 (1992), interprets that protection. These authorities address different taxes and activities. Review nexus separately for each state, including remote sales and post-move operations, before projecting that redomestication will eliminate a former state's tax burden.
Specific legal requirements to transfer a corporation to Texas from Vermont
Vermont has state-specific statutory, approval, filing, fee, and sequencing requirements that must be coordinated with Texas law. The requirements below are the origin-state requirements applicable to this transaction.
- Vermont authorizes outbound domestication for LLCs and business corporations under separate statutes. An LLC uses 11 V.S.A. § 4152 and the related provisions in sections 4153 through 4156. A business corporation uses 11A V.S.A. §§ 11.13 through 11.17. Confirm that Texas permits the corresponding transaction and that the entity's governing documents allow it. A Vermont LLC statute does not establish the approval or surrender procedure for a Vermont corporation.
- The LLC plan must be recorded and complete. Section 4152(c) requires the company's name and governing jurisdiction before and after domestication, the terms and conditions, the treatment of membership interests and other consideration, and the destination organizational documents that are or will be in a record. Attach the proposed destination articles and operating agreement. Identify whether management, distribution rights, voting rights, or ownership percentages will change. The approved plan should connect the existing Vermont business to its continuation in Texas.
- LLC approval follows 11 V.S.A. § 4153, which calls for consent by all members, subject to section 4156's protections concerning personal liability. Review the operating agreement and the applicable limits on its effect before documenting consent. Do not treat a manager's signing authority as proof of member approval. If the plan is amended, confirm that the amendment receives the consent required by the statute and the plan rather than relying on signatures approving an earlier version.
- Corporate approval has its own hierarchy. Under 11A V.S.A. § 11.14, the corporation follows the domestication vote specified in its organizational documents. If none is specified, it looks to the documents' merger vote, and then to the statutory merger vote where the documents also omit that standard. Address the board and shareholder actions required by the applicable corporate provisions. Identify separate class rights and any protected interest holder before soliciting approval. The LLC's all-member rule should not be copied into corporate instructions as a universal standard.
- For an LLC, the public Articles of Domestication are governed by 11 V.S.A. § 4154. They identify the company and governing jurisdiction before and after domestication, state that it has domesticated from or into another jurisdiction, provide the effective date under the destination law, and address the required approval. If the resulting foreign LLC will not be authorized to transact business in Vermont, provide the statutory street and mailing addresses for service-related purposes. The destination filing does not replace these Vermont articles.
- An outgoing Vermont LLC must also surrender its Vermont organizational certificate. 11 V.S.A. § 4155(c) requires a filed statement identifying the company, surrendering the certificate in connection with foreign domestication, confirming approval, and naming the destination jurisdiction. This is distinct from the Articles of Domestication content in section 4154. Make the surrender requirement explicit in the closing documents and confirm how the filing office processes the instruments. Ordinary dissolution and liquidation documents do not describe the same transaction.
- Corporate Articles of Domestication are governed by 11A V.S.A. § 11.15. The additional accompanying information depends on the result: a corporation remaining authorized to transact business in Vermont must address the application for a certificate of authority, while an outgoing corporation without Vermont authority provides the specified service address. Section 11.16(c) separately requires the statement surrendering the Vermont organizational record. Identify these requirements in the corporate filing instructions rather than describing a single LLC surrender form as sufficient for both entity types.
- Outbound effectiveness follows the destination's governing statute. Section 4154(b)(2) supplies that rule for an LLC, and section 11.15(c)(2) does so for a business corporation. Coordinate the date stated in the Vermont articles with the actual Texas filing. Retain the accepted documents and confirm the resulting public record in each jurisdiction. An internal plan can specify a desired closing date, but the filings must establish a legally effective transaction. Do not cancel the Vermont agent solely because the owners approved the plan.
- Under section 4155(a) for LLCs and section 11.16(a) for corporations, the domesticated business remains the entity that existed before domestication. Property stays vested, obligations continue, and pending proceedings are preserved under the statutory rules. The transaction ordinarily does not dissolve the entity for winding-up purposes. Preserve the evidence of continuation for lenders, banks, title insurers, and licensing agencies. Federal tax treatment and EIN consequences are separate questions; neither follows conclusively from the Secretary of State's acceptance of the filing.
- Vermont preserves jurisdiction over existing obligations. The LLC statute expressly provides continuing jurisdiction and a Secretary of State service mechanism for the covered foreign LLC. The corporate filing provision likewise requires service-address information where the resulting foreign corporation lacks Vermont authority. Use an address that will remain monitored, and update the responsible person's contact information in the closing record. Domestication does not eliminate a preexisting claim, discharge a guaranty, or prevent enforcement merely because the entity's registered office moves elsewhere.
- The statutory fee for LLC Articles of Domestication is $20 under 11 V.S.A. § 4012(a)(19). Corporate domestication fees are addressed separately in 11A V.S.A. § 1.22. Calculate any additional surrender instrument, foreign-registration filing, destination charges, and requested certificates separately. The domestication fee does not include tax liabilities, overdue annual reports, or legal services. Confirm the complete filing packet with the current Secretary of State business-filing guidance.
- Ordinary Vermont LLCs and profit corporations file annual reports. They should not be described as subject to a general biennial reporting cycle. The Secretary of State's report instructions specify the first three months after fiscal year-end for LLCs and the first two and one-half months for profit corporations. For a calendar-year entity, those periods ordinarily end March 31 and March 15, respectively. Foreign registration after domestication can preserve annual-report obligations and can carry a different fee from domestic registration. Section 4012 lists $45 for a domestic LLC annual report and $170 for a foreign LLC annual report. A company keeping Vermont operations should include that difference in its ongoing compliance budget. These Secretary of State fees are separate from the $250 business-entity minimum tax; paying one does not satisfy the other. Reconcile both agencies' records, including the fiscal year and the exact legal name, before setting the post-domestication calendar.
- Before closing, review Vermont real estate, sales-tax registration, payroll accounts, professional licenses, and material contracts. A company that continues Vermont business must evaluate foreign qualification and ongoing tax filings; a company ending activity should satisfy final returns before closing accounts. Vermont's 2026 estate-tax filing-threshold change and federal-conformity changes can also affect the owner's separate planning. Keep personal residency decisions distinct from the entity filing and retain the signed plan, approvals, articles, surrender statement, and destination evidence together as the permanent domestication record.
